
Business plan template
Dog grooming salon
One-person appointment-based grooming for small and medium dogs; boarding, transport and veterinary care excluded.
The project
What this template helps you prepare
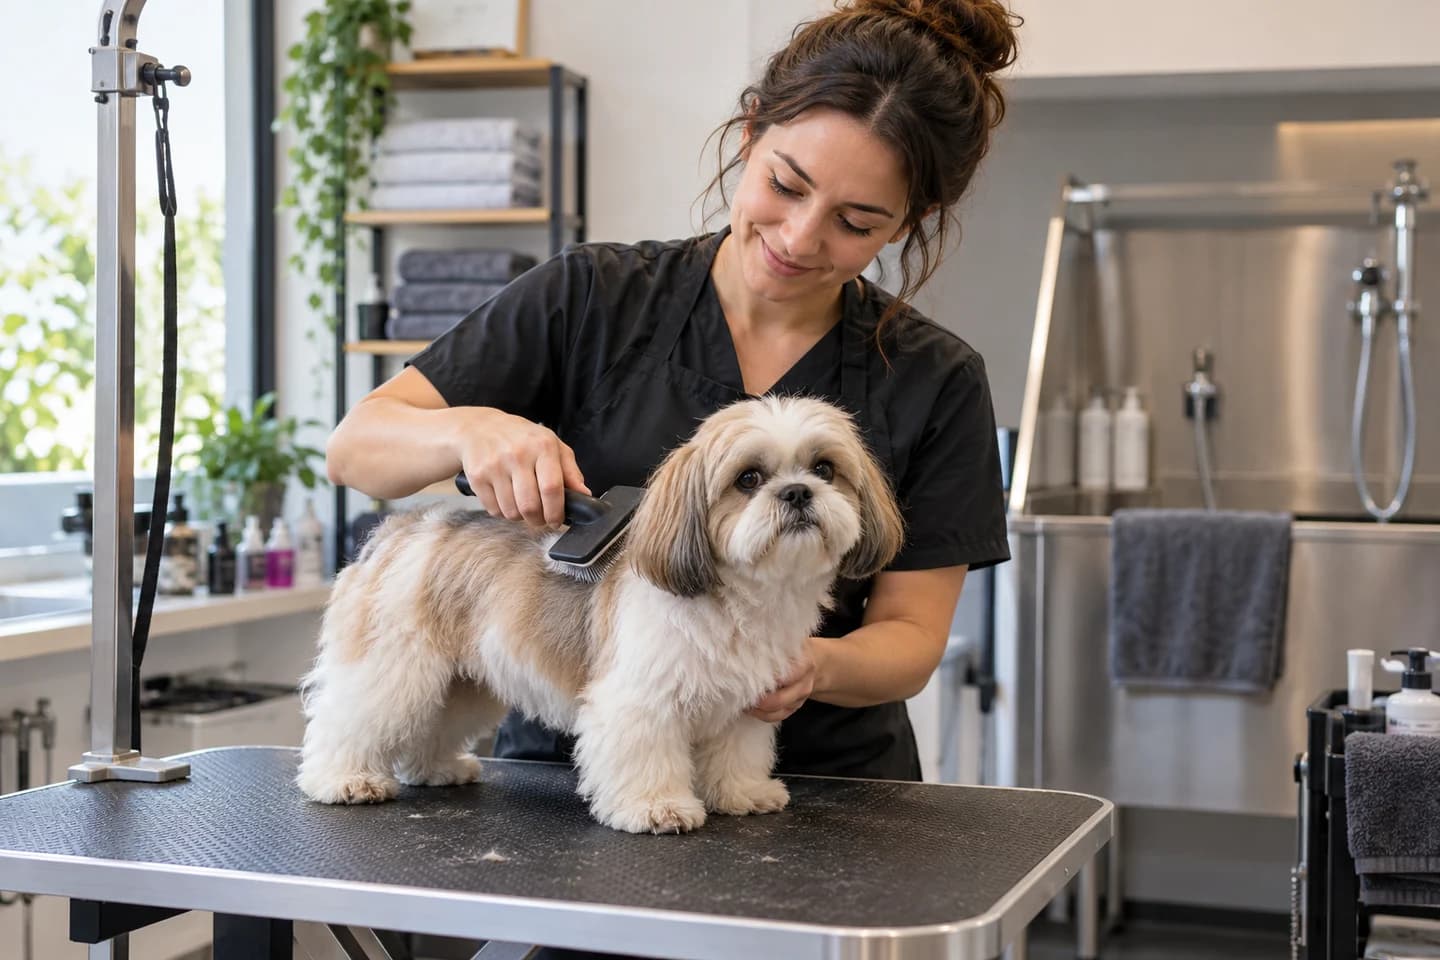
The salon provides washing, drying and clipping according to coat and condition. Quotes state detangling supplements before work. The example sells neither boarding nor food and performs no veterinary procedures.
Assess demand
Survey dog types, local rates and booking lead times. Aux soins des 4 pattes shows effects of breed, coat and time; it does not guarantee a new salon’s basket. Large dogs are excluded from the central mix.
The figures
A fictional case to explain the calculations. The amounts below are neither industry averages nor profitability targets.
- Sales over 12 months
- €38,100
- Profit over 12 months
- €1,576
- Lowest cash balance over 36 months, before the deposit reserve
- €18,093
The director’s planned remuneration
The result in this example assumes lower remuneration at startup, followed by increases according to the schedule below.
- Months 1 to 3
- €250 gross per month
- Months 4 to 6
- €400 gross per month
- Months 7 to 12
- €650 gross per month
- Months 13 to 36
- €1,100 gross per month
Year 1: €5,850 gross paid to the director, costing the business €8,483 with the assumed employer contributions.
These amounts are before employee contributions and personal income tax. The director’s personal budget and the resources to cover it during startup must be planned separately; no benefits are assumed.
Coat matters to price as much as weight
Two dogs of the same size may require very different times. Coat condition and tolerance of handling should be discussed before confirming a booking. The example average works only if the mix fits the ninety-minute allowance.
Drying and cleaning remain working time
Clipping occupies only part of the appointment. Washing, drying, owner handover and cleaning also occupy practitioner and equipment. Another bath therefore does not double a solo salon’s capacity; calculation must follow total time per animal.
Build the financial forecast
The assumptions behind the figures
Pricing and average sale
€60 excluding VAT per unit is the example price. The fictional €72 VAT-inclusive price compares with published small and medium dog ranges; it is not a national average. Size and condition must match the assumed time.
Volume and ramp-up
The schedule assumes 635 units in year one, from 30 in the first month to a monthly maximum of 75 over 36 months. Replace these assumed sales with orders, bookings or local counts. Appointments ramp up with lower August activity; no subscription guarantees repeat frequency.
Sales-related costs
€6 excluding VAT per unit is a direct-cost budget without an obtained supplier quote. Shampoo and consumables follow appointments; water, energy, linen and sharpening also have fixed allowances. Confirm drying consumption and plumbing quotes. The example adds card fees of 1.75% of VAT-inclusive sales on all receipts using the SumUp comparison; no negotiated rate is assumed.
Time and production capacity
The example reserves 90 minutes per unit within 120 monthly hours of direct capacity. Remaining time must cover administration, prospecting and absences; check the weekly schedule before adopting the limit. Each appointment reserves ninety minutes including intake and cleaning; the example does not count two dogs worked simultaneously.
The parameters that matter
Before using the template figures, check how these points apply to your project.
Which dogs and coat conditions are accepted?
Which supplements are stated before grooming?
What are full hot-water and drying costs?
Scope to keep in mind
Small and medium dog grooming without boarding, transport, large dogs or medical procedures. Verify premises, animal welfare and insurance for the exact service.
Sources and references
Template last revised: 25 October 2026
- Simulateur de revenus du dirigeant de SASU
Simulateur consulté le 15 octobre 2026 ; paramètres réglementaires selon l'année choisie. SASU à l'IS ; décomposition employeur et salarié. Les paramètres individuels et les exonérations changent le coût. Méthode de remplacement du taux forfaitaire du cas. Aucune simulation nominative n'a été produite ; 45 % n'est pas un taux certifié par cette page.
- Tout savoir sur la TVA
Dossier officiel actualisé en mars 2019, consulté le 15 octobre 2026 ; taux normal également recoupé avec le résultat de recherche de l’article 278 du CGI. Taux normal ; les dix cas sont limités à des opérations intérieures au taux normal. Règle du profil France existant ; les taxes et taux futurs doivent être revérifiés avant utilisation.
- Impôt sur les sociétés taux déclaration paiement
Règles consultées le 15 octobre 2026. Taux normal ; éligibilité au taux réduit soumise à conditions. Les cas n'activent pas le taux réduit faute de vérification du capital et de la détention. Le calcul utilise le paquet France existant.
- Tout savoir sur la cotisation foncière des entreprises
Règles et barèmes 2026. Exonération l'année civile de création ; montant ultérieur dépendant notamment de la commune et de la base. Charge explicite en décembre des années suivantes. Les 600 ou 1 200 euros des cas sont des budgets fictifs, pas des montants tirés du barème de base minimum.
- Rémunération du mandat du président de SAS
Fiche consultée le 25 octobre 2026. Mandat social du président de SAS, éventuellement exercé à titre gratuit, avec rémunération fixe ou variable décidée selon les règles de la société. Ne décrit pas un contrat de travail salarié. Cadre de la rémunération progressive du mandat. Aucun montant, taux de cotisations ou besoin personnel du dirigeant n’est confirmé par cette source.
- Tarif des prestations de toilettage
Page consultée le 25 octobre 2026 ; date d’effet non indiquée. Salon à Charny ; prix selon race, pelage, état et temps passé. Comparer un mélange de petits et moyens chiens ; pas une moyenne nationale.
- Tarifs de paiement en personne
Page consultée le 25 octobre 2026 ; date d’effet non indiquée. Paiements en personne, formule sans abonnement ; autres formules et paiements en ligne distincts. Le cas physique suppose tous les encaissements par carte à 1,75 % du TTC, sans frais fixes par opération. Remplacer selon le contrat.
Template version : 1.0.0-draft.1